
 (1).png)
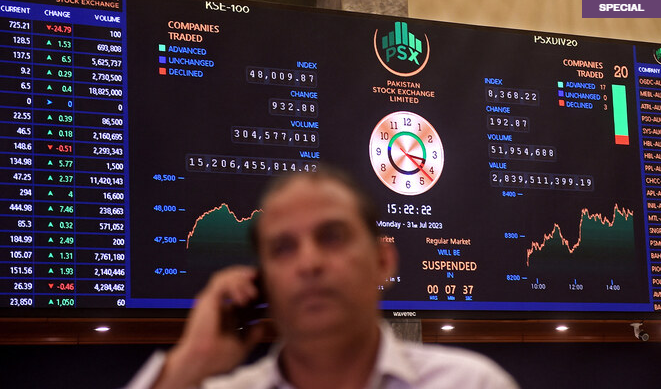
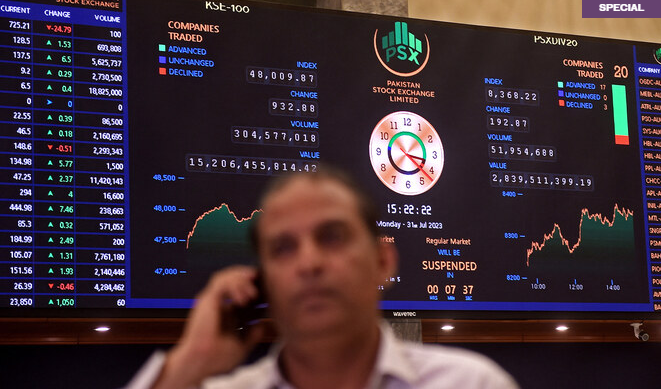
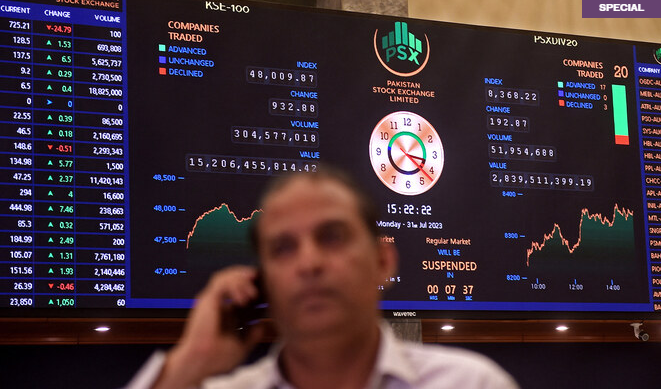
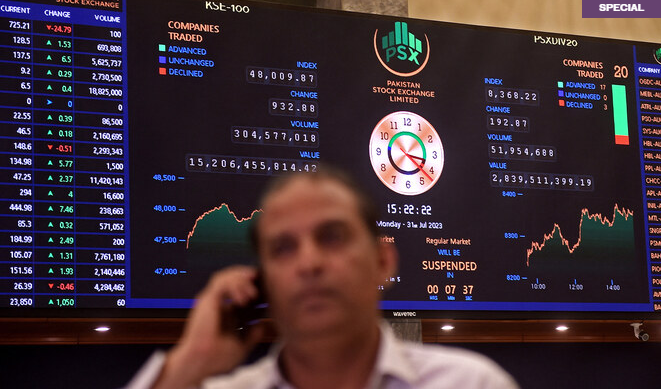
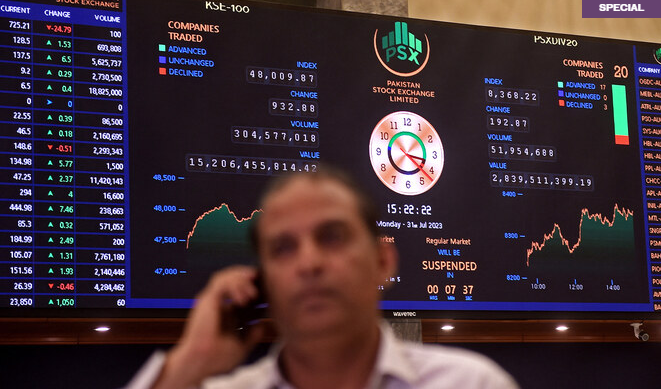
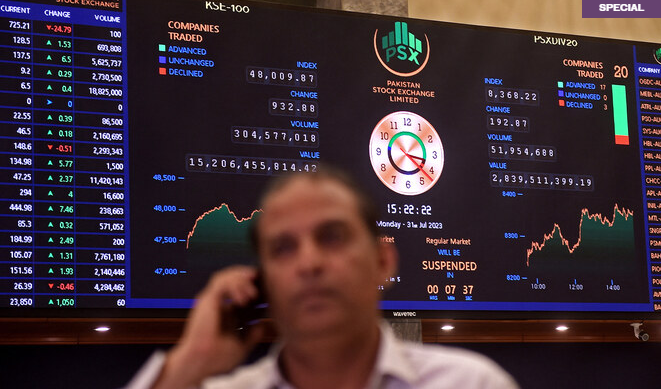
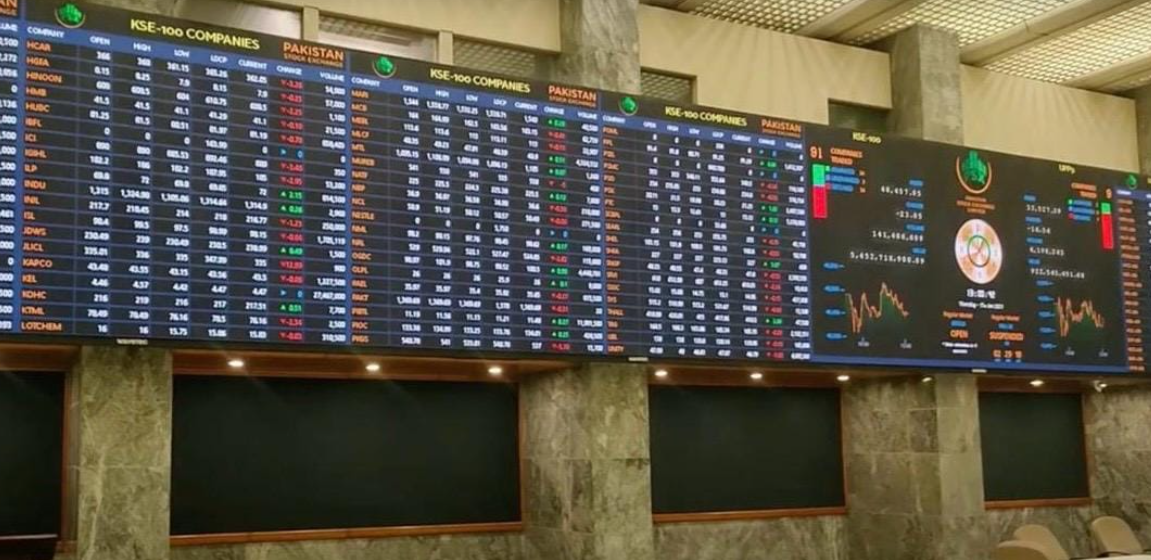
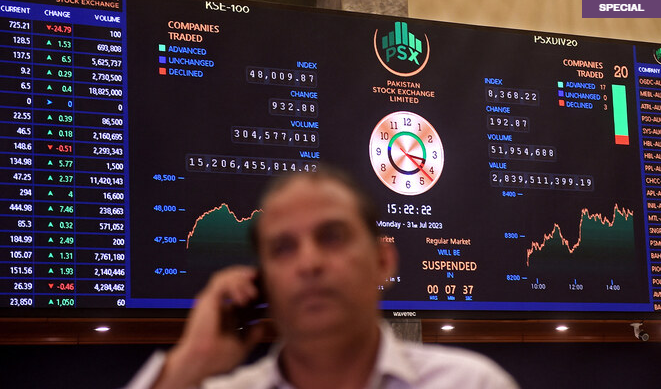
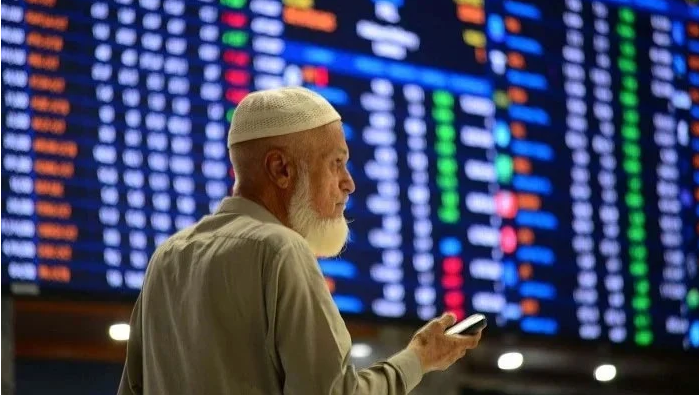
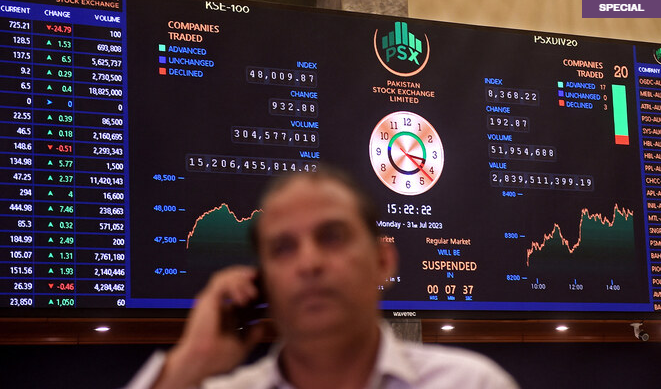
The Pakistan Stock Exchange (PSX) extended its bullish momentum during the week ended July 31, 2026, with the benchmark KSE-100 Index advancing 5,072.92 points, or 2.97%, to close at 176,094.12, compared with 171,021.20 a week earlier.
Investor sentiment remained firmly positive throughout the week, supported by broad-based buying across heavyweight sectors. The rally was driven primarily by commercial banks, fertilizer and cement companies, while confidence received an additional boost after the State Bank of Pakistan (SBP) kept the policy rate unchanged at 11.5%. Improving macroeconomic indicators, easing inflation expectations and a steady flow of strong corporate earnings further strengthened market participation.
Market Capitalization
The PSX's total market capitalization increased by Rs137.30 billion during the week, rising from Rs4.866 trillion to Rs5.003 trillion.
In US dollar terms, market capitalization climbed by approximately $498.5 million, increasing from $17.51 billion to $18.01 billion. After adjusting for exchange rate movements, the market delivered a 2.99% USD-adjusted weekly return, reversing the previous week's negative performance.
Macroeconomic Developments
Several positive economic developments supported investor confidence during the week:
- The SBP maintained the policy rate at 11.5%, while projecting FY2027 GDP growth of 3.5%–4.5% and foreign exchange reserves of $20.2 billion by year-end.
- Weekly Sensitive Price Indicator (SPI) inflation declined 0.91%, although annual inflation stood at 9.05%.
- Pakistan's Business Confidence Index improved to 52.4, reflecting stronger business sentiment.
- The Consumer Confidence Index remained broadly stable at 35.8, supported by easing inflation expectations.
- The SBP also reported net foreign exchange purchases of $7.11 billion during FY26, including $635 million purchased from the interbank market in April.
Sector Performance
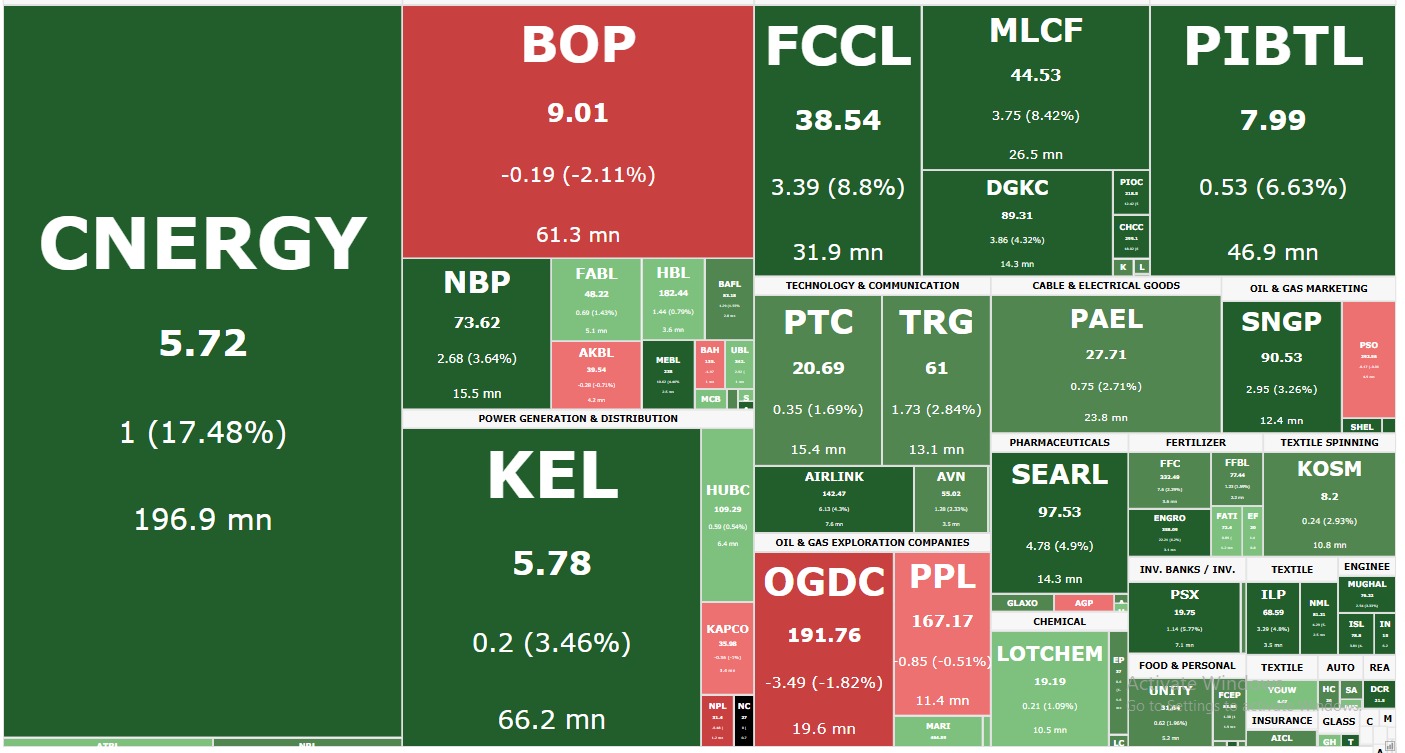
The week's advance was led by Commercial Banks, which contributed 1,951.68 points to the KSE-100 Index.
Other major contributors included:
- Fertilizer: +970.43 points
- Cement: +524.23 points
- Oil & Gas Exploration Companies: +393.69 points
- Investment Banks & Securities Companies: +241.71 points
- Automobile Assemblers: +206.88 points
- Power Generation & Distribution: +119.09 points
- Textile Composite: +118.10 points
- Insurance: +109.13 points
- Refineries: +94.30 points
Additional support came from Oil Marketing Companies, Food & Personal Care, Technology, Pharmaceuticals, Transport, Engineering, Cable & Electrical Goods, Chemicals and several other sectors.
Only a handful of sectors closed the week in negative territory, including Leasing Companies, Textile Weaving, Automobile Parts & Accessories, Sugar & Allied Industries, REITs, Miscellaneous, and Closed-End Mutual Funds.
Top Stock Contributors
Among individual stocks, Fauji Fertilizer Company (FFC) emerged as the largest contributor to the benchmark, adding 886.28 points.
Other major positive contributors included:
- United Bank Limited (UBL): +816.63 points
- Meezan Bank (MEBL): +329.28 points
- Habib Bank Limited (HBL): +240.73 points
- Engro Holdings (ENGROH): +197.57 points
- Bank Alfalah (BAFL): +133.24 points
- National Bank of Pakistan (NBP): +127.48 points
- Lucky Cement (LUCK): +122.10 points
- Pakistan Petroleum Limited (PPL): +120.28 points
- Mari Energies (MARI): +112.92 points
On the downside, Systems Limited (SYS) was the biggest drag on the benchmark, erasing 60.23 points, followed by PIOC, TPLRF1, HGFA, HMB, PSEL, JDWS, FFL, INIL, and THALL.
Investor Activity (FIPI/LIPI)
Foreign investors remained net sellers during the week, recording net equity sales of Rs912.76 million (approximately $3.28 million).
The selling was mainly driven by Foreign Corporates, which offloaded Rs1.68 billion worth of equities. However, Overseas Pakistanis remained net buyers with purchases of Rs759.41 million, while Foreign Individuals posted marginal net buying.
Domestic institutional investors continued to provide strong support to the market. Mutual Funds emerged as the largest buyers with net purchases of Rs4.07 billion, followed by:
- Broker Proprietary Trading: Rs648.75 million
- Insurance Companies: Rs190.35 million
- Other Organizations: Rs148.11 million
Meanwhile, Individuals were the largest domestic sellers, offloading Rs3.30 billion worth of equities. Banks/DFIs recorded net selling of Rs591.26 million, while Companies and NBFCs also remained net sellers.
Outlook
The KSE-100 Index ended the week on a strong footing, supported by improving macroeconomic fundamentals, stable monetary policy, easing inflation expectations and encouraging corporate earnings. Continued institutional buying and positive economic indicators are expected to remain key drivers of investor sentiment, although foreign fund flows and upcoming corporate results will continue to influence market direction in the weeks ahead.




















































































Add a comment